POPULAR FOR FIRST-TIME BUYERS
FHA Loans
Flexible financing with down payments as low as 3.5% for qualified borrowers.
Let's discuss FHA ↗
Buying your first home, moving up, or looking for a smarter mortgage? I'll help you understand your options and find a path that fits your life.
WELCOME HOME
Every homebuyer has a different story. That's why I take the time to learn yours, explain the numbers, and explore loan programs that traditional one-size-fits-all approaches might miss.
Get to know my approach ↗FINANCING THAT FITS
From traditional mortgages to more flexible paths to homeownership, explore options that may work for you.
Flexible financing with down payments as low as 3.5% for qualified borrowers.
Let's discuss FHA ↗Powerful mortgage benefits for eligible veterans, service members, and qualifying spouses, including potential zero down payment.
Explore VA ↗Potential 100% financing for eligible buyers and properties in qualifying rural and suburban areas.
Explore USDA ↗Flexible choices for purchase or refinance, including low-down-payment options for qualified buyers.
Explore conventional ↗Explore eligible assistance programs that may help reduce the money needed upfront.
Find assistance ↗Alternative income documentation options for eligible self-employed borrowers and business owners.
See my options ↗Ask about financing paths for applicants with an ITIN or other nontraditional qualification needs.
Let's talk ↗Financing solutions for higher-priced properties, with qualification and product features varying by program.
Explore jumbo ↗Review your current loan and explore options to adjust terms, access equity, or potentially reduce payments.
Review my loan ↗Ask how eligible temporary buydown structures may lower initial payments during the early loan years.
How buydowns work ↗Learn about alternative homeownership solutions, including select lease or equitable-title arrangements.
Explore pathways ↗Every scenario is different. Let's explore possibilities together.
Ask Matt ↗All loan programs are subject to credit approval, income, property, eligibility, and applicable underwriting requirements. Availability, terms, and minimum down payments vary. Rent-to-own and equitable-title options may be offered through third parties and are not necessarily mortgage loan products.
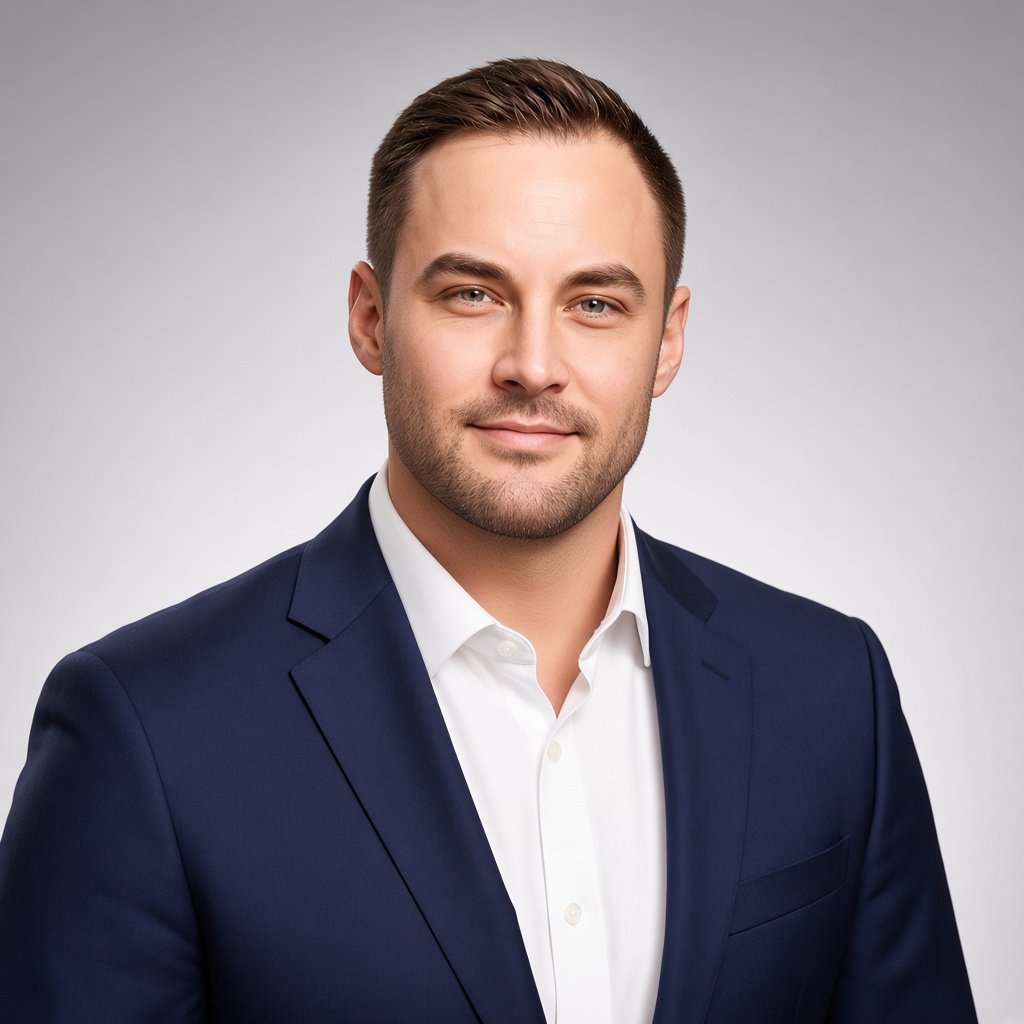
MATT COMBS
THE PERSONAL DIFFERENCE
I'm Matt Combs, a mortgage loan originator who believes getting a mortgage shouldn't feel confusing or impersonal. Whether it's your first purchase or your fifth, you deserve clear communication, honest answers, and someone who takes your goals seriously.
FOR HOMEBUYERS
On eligible purchase loans, I offer a temporary 1-year rate buydown at no added cost to you. A temporary buydown reduces your monthly payment during the first year of the loan, giving you breathing room while you settle into your new home.
Not all borrowers will qualify. This is not a commitment to lend or an offer of specific rates or terms. Contact Matt for details.
FOR REAL ESTATE AGENTS
Clear communication with you and your clients, from preapproval to closing.
Proactive status updates so you and your buyers know where the loan stands.
Prompt preapproval letters and a buydown option on eligible loans that can help buyers feel confident.
FHA, VA, USDA, conventional, jumbo, down payment assistance and non-traditional programs.
YOUR ROADMAP
You don't need to know everything about mortgages. That's what I'm here for.
Tell me about your goals, timeline, and what matters most.
We'll compare loan programs and discuss possible next steps.
We'll work through application, documentation, and approvals.
Move toward closing with a clear picture of the process.
HAVE A QUESTION?
Text, call, or send me a note. No pressure. Just a starting point.
GOOD TO KNOW
It depends on the loan. Some FHA loans allow as little as 3.5% down, certain conventional programs allow 3%, and eligible VA and USDA borrowers may qualify for zero down. Eligibility and closing costs vary.
Potentially! Depending on your circumstances, traditional tax-return-based underwriting or alternative options such as bank-statement programs may be available.
Often, yes. Seller contributions are permitted under many mortgage programs, subject to transaction-specific limitations. I can explain the rules for your loan type.
For an eligible loan, a temporary buydown may subsidize your payments during the initial period. Your permanent note rate and full payment still apply after the subsidy expires. The benefit and funding rules depend on the program.
Reach out. We can discuss your income, credit, down payment, goals, and other details to see which programs may be appropriate. No loan approval is guaranteed.
LET'S GET STARTED
Have a question or want to explore a mortgage option? Send a quick note or contact me directly.
☎Complete the fields below. Your email app will open with a prefilled message to Matt.